
Friday, 16 October 2026European Markets

Autonomous delivery robots now operate across 20 US cities as Europe lags in regulatory framework

Serve Robotics has deployed autonomous delivery fleets across 20 cities and 6 major US metro areas, partnering with Uber Eats and DoorDash to cover 80% of America's delivery market. The commercial-scale deployment highlights a regulatory gap: US cities are approving sidewalk robots while European capitals still debate classification and liability frameworks.

LM Salvado
LM Salvado

March 15, 2026

Autonomous delivery robots now operate across 20 US cities as Europe lags in regulatory framework
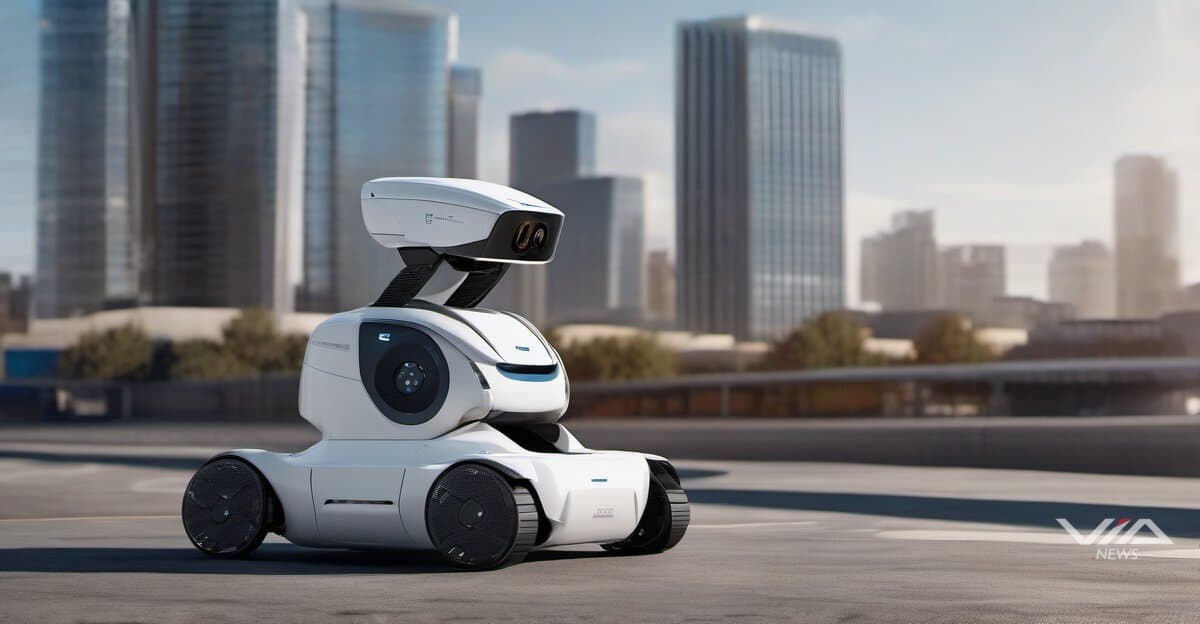
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.
Loading stream...

Serve Robotics operates autonomous delivery robots across 20 cities spanning 6 major US metro areas, from Los Angeles to Washington D.C. The company partners with both Uber Eats and DoorDash, giving it access to over 80% of the American delivery market.

The deployment scale indicates autonomous robotics has cleared key operational barriers. Multi-platform integration, previously a technical challenge, now functions across competing delivery networks. Regulatory approvals, once slow and fragmented, are accelerating as cities develop sidewalk robot frameworks.

European cities face a different trajectory. London, Paris, and Berlin lack unified regulatory approaches for sidewalk autonomous vehicles. The EU's proposed AI Act classifies delivery robots as "limited risk" systems, but member states retain authority over public space usage. Germany requires human supervision within visual range. France restricts robot weight and speed. Spain debates whether robots need insurance as vehicles or liability coverage as service providers.

This regulatory fragmentation puts European robotics companies at a disadvantage. Starship Technologies, an Estonian company, operates more robots in US college campuses than in European city centers. The company deployed 2,000+ robots globally but faces permit delays in EU capitals.

The commercial implications extend beyond delivery services. Autonomous robotics companies need operational scale to train AI systems and reduce per-unit costs. US competitors gain this advantage through multi-city deployments while European firms navigate 27 different regulatory regimes.

Investment patterns reflect this gap. US autonomous delivery companies raised $1.2B in 2025, compared to €340M for European competitors. Venture capital flows toward markets with clear deployment paths.

The European Commission recognizes the challenge. A proposed directive on autonomous ground vehicles aims to harmonize rules by 2027, but member states disagree on liability standards and data collection limits. Until resolution, European cities will struggle to match the deployment density seen across American metro areas.

The robotics regulatory gap mirrors earlier challenges with ride-sharing and e-scooters, where European cities lagged US counterparts by 2-3 years in establishing operational frameworks.
LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Biopharma Catalyst Cluster: Late-Stage Readouts and Regulatory Milestones
October 2026 brings a dense run of Phase 3 wins (ALOFT-IPF, RESTORE-3), new data presentations (Roche, Bayer, Lilly, Vertex, Galderma) and regulatory steps (FDA acceptance of Roche's vamikibart BLA, Scholar Rock's EMA resubmission). The next big catalyst is the ivonescimab FDA PDUFA date on 2026-11-14. Obesity combination studies (REDEFINE 4, TOGETHER-PsO) and the 2027 Maritime-1 completion point to more catalysts ahead. QAIAx's speculative AI-linked trial claims (the QIII pilot, targeted for 2027) are an unrelated micro-cap sideshow with weak evidence, and have little in common with the large-cap pipeline news.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,986
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,986 facts checked against source5,378 source documents archived
Query this data → isubstrate.com